Life of a Medical Claim: From Doctor’s Visit to Payment
A simple guide to understanding how health insurance claims work and where problems can arise
Table of Contents
- Behind every doctor’s visit: How a medical claim really works – Why understanding the life of a claim matters for employers, employees, and providers.
- It all starts with a doctor’s Visit – How claims begin with CPT codes and electronic submissions.
- The network adjusts the bill – How network contracts reduce billed amounts and control costs.
- Claims administrator reviews – The TPA’s role in verifying coverage and splitting costs.
- Where things can go wrong – Common claim errors and how clear communication prevents them.
- Funding the claim – How the claims fund works and how Trinity ensures accurate payments.
- The explanation of benefits (EOB) – Understanding your EOB and what it tells you.
- Timing and deadlines – How long claims take to process and key filing timeframes.
- From service to payment: Understanding builds trust – Why transparency and partnership with Trinity matter.
- Key Takeaways – Quick summary of what to remember about the life of a medical claim.
Behind every doctor’s visit: How a medical claim really works
If you’ve ever wondered what really happens after you visit the doctor, you’re not alone.
For most people, what takes place behind the scenes of a medical claim feels like a mystery: full of codes, forms, and waiting. But understanding this process matters more than you might think.
Every medical claim represents part of someone’s health story. From the doctor’s office to the claims administrator, each step is designed to make sure the right care is covered at the right cost.
For employers, this means managing benefit dollars wisely. For employees and their families, it means confidence that their care is handled with accuracy and fairness. And for providers, it ensures that services are recognized and reimbursed properly.
At Trinity, we believe that transparency and compassion go hand in hand. That’s why we’re breaking down the life of a medical claim in simple, clear language so you can see exactly what happens between your doctor’s visit and final payment, and feel assured that every step is guided by trust and integrity.
It all starts with a doctor’s visit
Every medical claim begins with something simple: a visit to the doctor. After your appointment, the provider’s office sends an electronic claim to your health plan. Think of this as a detailed “receipt” of your visit, explaining what services were provided and how much they cost.
Each service listed on the claim is identified by a CPT code (short for Current Procedural Terminology). These codes aren’t unique to your plan; they’re used nationwide to describe every medical service in a standardized way. For example, a routine office visit, a blood test, or an X-ray all have specific CPT codes that help insurance systems understand exactly what was done.
Let’s say you went in for a regular check-up. Your provider would enter the CPT code that corresponds to an office visit and send that claim electronically to the network for review. From there, the claim begins its journey through the rest of the process by being checked, adjusted, and approved until it’s finally paid.
The network adjusts the bill
Once the doctor’s office submits the claim, it goes to the network: the group of healthcare providers who have agreed to work with your plan. This is where the first important adjustment happens.
Every provider in the network has a contracted rate for their services (a pre-negotiated amount that’s usually lower than what they would charge on their own). For example, a doctor might bill $200 for an office visit, but because they’re part of the network, the agreed rate for that visit might only be $100.
This process is called repricing, and it’s one of the biggest ways members and employers save money. The difference between the billed amount and the contractual amount is simply removed before the claim moves forward. The network ensures that everyone is paid fairly based on those agreements.
In short, this step turns a high medical bill into a fair, contracted cost, helping control expenses while keeping care accessible for members.
Claims administrator reviews
After the network adjusts the bill, the claim is passed to the claims administrator, also known as the Third-Party Administrator (TPA). The TPA’s job is to make sure everything about the claim is correct and covered according to the member’s health plan.
Think of the TPA as the “quality control” step of the process. Their team reviews the details carefully, checking three key things:
- The service matches the diagnosis.
They make sure the procedure or treatment makes sense for the reason it was given. - The service is covered under the plan.
Each plan has its own set of covered benefits, and the TPA ensures this service is one of them. - The costs are split correctly.
The TPA determines what portion of the bill is the member’s responsibility (such as a copay, deductible, or coinsurance) and what portion the health plan will pay.
For example, if the network’s contractual amount for a visit was $100 and the member already paid a $25 copay at the doctor’s office, the TPA will confirm that the health plan owes the remaining $75.
This step ensures fairness for everyone involved (the provider, the member, and the employer) before any payment is made.
Where things can go wrong
Even with all the checks in place, mistakes can happen and when they do, they can delay payment or cause confusion for everyone involved. Most claim issues start with something small but easy to fix once you know what to look for.
One of the most common problems is when a provider’s office uses the wrong CPT code. Since each code represents a specific service, even a minor mix-up can make the claim look incorrect and cause it to be denied or delayed.
Another frequent issue is when a claim is sent to the wrong network. This can happen if a member doesn’t share their updated insurance information or if the provider’s office doesn’t recognize the network listed on the member’s ID card. When this happens, the provider might mistakenly tell the member that the service “isn’t covered,” when it actually is and it was just sent to the wrong place.
Sometimes, outdated or missing insurance details also cause trouble, leading to back-and-forth communication before the claim can be corrected.
While these errors can be frustrating, they’re usually easy to resolve once identified. Trinity’s focus on clear communication and member advocacy helps reduce these errors, keeping claims processing smoother for both members and providers.
Funding the claim
Once the claim is approved, it’s time for payment and that’s where the claims fund comes in.
Each employer that partners with Trinity has a dedicated claims fund, which is like a special account set aside to pay for their employees’ medical expenses. Every month, the employer deposits a set amount into this fund. That amount covers expected claims costs, along with administrative fees, stop-loss insurance, and sometimes pharmacy expenses.
When the claims administrator (TPA) finishes reviewing a claim and determines what the plan owes, they send a request to Trinity. For example, if a member had a $25 copay and the plan owes the remaining $75, the TPA will ask Trinity to release $75 from the employer’s claims fund.
Trinity then transfers that amount to the claims administrator, who pays the doctor or facility directly.
It’s a simple but powerful system ensuring that providers get paid accurately, members aren’t overcharged, and employers maintain full transparency over how their healthcare dollars are used.
The explanation of benefits (EOB)
After a claim has been processed, the member receives a document called an Explanation of Benefits (EOB). Despite the name, the EOB isn’t a bill, it’s a summary that explains how the claim was handled and what costs were covered by the health plan.
The EOB lists important details such as:
- The provider’s billed amount.
- The network’s discounted (contractual) amount.
- What the plan paid.
- What the member may still owe such as a copay, deductible, or coinsurance.
For example, the EOB might show that a service wasn’t covered under the plan or that the cost was applied to the member’s deductible instead of being paid outright.
This document is essential because it keeps everything transparent. It helps members understand where their money went, what the plan covered, and why certain amounts appear on later bills.
At our company, we see the EOB as more than just paperwork, it’s a tool for clarity, trust, and accountability, helping members stay informed and confident in their health benefits.
Timing and deadlines
Just like any important process, medical claims follow specific timelines to ensure everything runs smoothly.
Once a provider submits a claim, it typically takes up to 30 days to review, approve, and process payment. During that time, the claim moves through all the necessary steps (from network repricing to claims administration and funding) before the provider is paid.
It’s also helpful to know that claims can be filed for up to two years after the date of service. This gives providers and members plenty of time to correct errors or submit claims that may have been delayed for any reason.
While the process may seem lengthy, these timelines are designed to protect everyone involved by giving enough time for accuracy, communication, and fairness in every step.
At Trinity, we work closely with our partners to make sure claims are processed efficiently, keeping payments on schedule and reducing unnecessary stress for members and employers alike.
From service to payment: Understanding builds trust
Every medical claim tells a story from the moment a member visits the doctor to the time the provider is paid. Along the way, each step plays a vital role in making sure care is covered correctly, costs are managed responsibly, and everyone involved is treated fairly.
Understanding the life of a claim helps remove confusion and empowers both employers and employees to take a more active role in managing their health benefits. It also highlights why choosing a trusted partner like Trinity makes a difference. With transparency, compassion, and strong administrative partnerships, Trinity helps ensure claims are handled efficiently, errors are reduced, and members receive the care and support they deserve.
At the end of the day, it’s about protecting people, fostering trust, and keeping healthcare simple and fair.
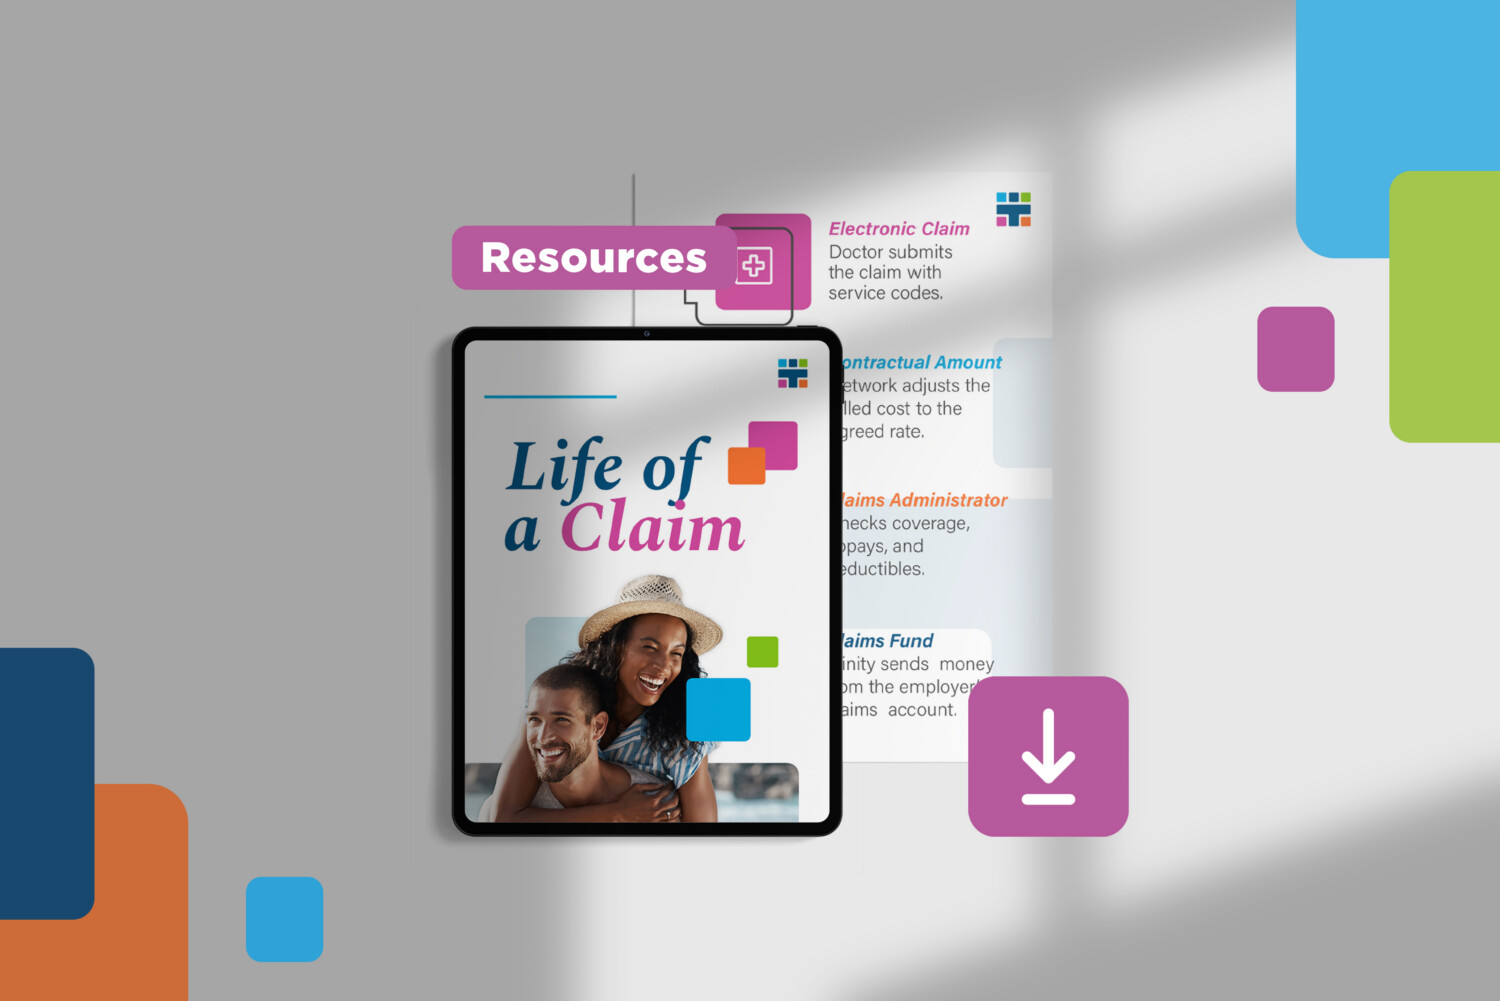
💡 Ready to see how it all fits together?
Download our visual guide to the Life of a Claim to explore the entire process at a glance (from doctor’s visit to payment) and discover how clarity in claims leads to better care for everyone.
Key takeaways
- Every medical claim follows a clear journey (from the doctor’s visit to final payment) to make sure care is covered fairly and accurately.
- CPT codes, network contracts, and claims administrators all play essential roles in keeping costs transparent and benefits easy to understand.
- Errors can happen, but with open communication and the right partner, they’re easy to identify and correct.
- Employers fund claims directly, giving them more control and visibility over healthcare spending.
- The Explanation of Benefits (EOB) keeps members informed about what was billed, what was paid, and what applied to their deductible.
- Trinity’s focus on trust, transparency, and compassion helps ensure claims are processed smoothly protecting both members and employers every step of the way.